Showing posts sorted by relevance for query Fed not printing money. Sort by date Show all posts

Wednesday, May 27, 2020

Monetary expansion Argentina-style

We are definitely sailing in uncharted monetary waters. In all of US history we've never come even close to today's monetary environment. Chart #1 is one that no economist ever expected to see coming out of the US:

Chart #1

In the 3 months leading up to May 11th (latest data available), the M2 measure of the US money supply has increased at an 82% annualized rate. In the past six months, it's up at a 40% annualized rate, and in the past year, M2 has increased by over 23%, and these numbers will go higher in the next week or two. This is serious, Argentine-style money growth. The big question now is whether so much monetary expansion will give us Argentine-style inflation.

Chart #2

Chart #2 shows the year over year growth rate of Argentina's M2 money supply, which is up 97% in the past year. From late 2010 through early 2018, Argentina's money growth averaged about 30% per year, and inflation was in the neighborhood of 25-30% per year. Given the recent surge in money creation, inflation in Argentina is going to be approaching 100% before too long.

Chart #3

Chart #3 shows what a decade or so of rapid money growth has done to the value of the Argentine peso. Since early 2007, the peso has fallen from just over 3 to the dollar to now 117; that translates into a 97.5% loss of value vis a vis the dollar. Since the Argentine government locked down the economy fiercely in order to fight Covid-19, revenues have all but dried up. The only way it can pay the bills is to literally print money. 

I've been an avid student of monetary policy and inflation ever since I spent four years living in Argentina in the late 1970s. Back then, inflation averaged about 125% per year, and during a visit to the country in the mid-1980s I was fascinated to watch hyperinflation unfold: prices almost tripled within the span of three weeks. In 2015 I wrote a post on the subject of inflation and Argentina, in which I explained that the conditions in Argentina that allowed a huge increase in inflation didn't exist in the U.S., despite the Fed's massive expansion of its balance sheet and the creation of trillions of dollars of bank reserves. Unlike the US, the government of Argentina relies on direct printing of money to finance its deficit, whereas the U.S. government finances its deficit by selling  bills, notes and  bonds. When the Argentine government needs to finance a budget shortfall, it can "borrow" money directly from its central bank in exchange for an IOU, which in practice is never repaid. In essence, the Argentine central bank simply runs the printing presses whenever the government needs money, and the government pays its bills with monopoly money.

Will the same happen to the US? I sincerely doubt it, but it's not impossible.

In 2013 I wrote a post entitled "The Fed is not printing money," which addressed in detail why the Fed's monetary expansion in the wake of the Great Recession was not inflationary. Over the years since then I have consistently argued that the Fed's huge expansion of bank reserves was unlikely to lead to higher inflation since the Fed was correctly supplying reserves to accommodate the banking sector's demand for safe assets (bank reserves are functionally akin to T-bills). Inflation only happens, as Milton Friedman taught us, when the supply of money exceeds the demand for it. And indeed inflation has remained relatively low and stable for most of the past decade—which in effect proves that the Fed was not "printing money."

The key feature of the US monetary system is that the Fed can not create money directly—only banks can do that. The Fed can, however, make it easier for banks to create money by increasing the supply of bank reserves. Banks need reserves in order to collateralize their deposits. The Fed creates reserves by buying securities (e.g., Treasury bills, notes and bonds, and more recently, mortgage-backed securities and some corporate bonds). In effect, the Fed buys securities and pays for them with bank reserves. But crucially, reserves are not money that can be spent anywhere. The Fed simply swaps reserves for notes and bonds, thus transmogrifying longer-term securities into short-term, risk-free securities. Reserves have become equivalent to T-bills, since they are default-free and pay a floating rate of interest.

In times of great uncertainty and surging money demand, like today, the Fed fills the market's need for short-term safe securities by buying riskier securities and paying for them with risk-free reserves. If banks don't want to hold the reserves they can use them to support increased lending, which indeed does result in a monetary expansion. But if that expansion exceeds the market's demand for money, then higher inflation will be the result. The fact that inflation so far has not risen is proof that the Fed's actions have not been inflationary. Excess reserves—which now total $3.2 trillion—have served to satisfy the banking system's demand for risk-free, short-term assets, and more recently to satisfy the public's demand for a massive increase in bank savings deposits and checking accounts, as shown in Chart #4, which in turn has been turbo-charged by all the uncertainties and disruptions caused by the Covid-19 panic:

Chart #4

Looking ahead, the most important question becomes, "What happens when the Covid uncertainties decline and the demand for risk-free assets declines?"

If the Fed does not reverse course in a timely manner (e.g., by selling notes and bonds and extinguishing bank reserves), then we will find ourselves flooded with unwanted money. And as Argentina has demonstrated, that can lead to a big increase in inflation.

And that is what my friend Nuni Cademartori is illustrating in the cartoon which follows. Too much money erodes the value of money. I've got stacks of million-peso Argentine notes printed decades ago that today are worth about the same as toilet paper.

Let's hope this does not come to pass in the US:


Monday, March 18, 2013

The Fed is not "printing money"

The idea that the Fed is "printing money" with abandon, and that this is seriously debasing the U.S. dollar, is a fiction borne of ignorance of how monetary policy actually works. Fed policy may indeed pose the risk of serious debasement in the future, but to date there is little or no evidence to suggest that this has occurred.


The above chart is a graphical depiction of how the Fed's balance sheet (in simplified form) has changed over the past six years, from a time in early 2007 when the economy was growing normally (although the housing correction was just beginning), to the situation today. The major changes: on the liability side, relatively normal growth of currency in circulation (see below for details), and gigantic growth in bank reserves; on the asset side, the elimination of T-bills, strong growth in T-bonds, and unprecedented growth and holdings of MBS and Agency securities. Put another way, the Fed has purchased about $2.36 trillion of T-bonds, MBS, and Agency securities, shed about $280 billion of T-bills, and in the process created $420 billion of new currency and $1.7 trillion of new bank reserves.


As the chart above shows, currency has grown at a 6.8% annualized rate since early 2007, the same rate that we have seen for the past 20 years. Currency actually grew at a faster rate from 1993 through 2003 than it has in the past six years, and the former was a period when inflation averaged 2.5%. In the past six years, inflation has averaged about 2.2%. So the recent growth in currency is nothing out of the ordinary, and does not necessarily imply higher inflation than what we have seen in recent decades. It is also important to note that the Fed only supplies currency on demand, in exchange for bank reserves. Thus, the Fed cannot "force-feed" currency to the world. The world holds only as much currency as it wants to hold, so growth in currency is not necessarily inflationary at all.


In addition to currency in circulation, the other major component of the Federal Reserve's liabilities is bank reserves, shown in the chart above. Here we see enormous growth, orders of magnitude in excess of historical experience. In fact, the Fed has expanded bank reserves by a factor of 18 in the past six years. Isn't this the same as "printing money?" No, because bank reserves aren't "money" and can't be spent anywhere. Bank reserves exist only as a liability on the Fed's balance sheet. Banks can exchange their reserves for currency, and currency can be spent, but as we saw above, currency has not grown by any unusual amount. Banks have instead been content to hold on to the majority of the reserves the Fed has created. This is due to the fact that the Fed started paying interest on reserves in 2008, which makes reserves functionally equivalent to T-bills, and the fact that banks have wanted to increase their capital and fortify their balance sheets, and bank reserves fit that bill.

In effect, the Fed has been doing nothing more than swapping newly-created bank reserves for bonds and currency, and the world and the banking system have been happy to participate in the swap. The Fed has taken duration risk out of the market and supplied low-risk and highly liquid assets in return. In a post last December, I described how in a way the Fed has been acting like the world's biggest hedge fund.


Banks can exchange their reserves for currency if the public demands it, or banks can hold on to their reserves if they want to increase their capital and fortify their balance sheets. The only other thing banks can do with their reserves is to support an increase in their deposits. In our fractional reserve banking system, banks must hold about one dollar of reserves for each ten dollars of deposits. Banks are the only ones who can "print money," and that is done by extending credit to borrowers. Given the increase in bank reserves, banks could theoretically have increased their lending and their deposits (which currently total about $8.7 trillion) by a factor of 18, or over $150 trillion. Obviously, nothing of the sort has happened.


As the chart above shows, the M2 measure of the money supply has grown only slightly more than 6% per year for the past 18 years. Since early 2007, M2 has grown at an annualized rate of 6.5%, about the same as currency. Again, there is no sign here of any usually fast growth as a result of the Fed's enormous expansion of bank reserves.


The proof is in the pudding: inflation by any measure has been averaging between 2 and 2.5% for the past six years, with no signs of any acceleration. We are thus forced to the conclusion that the Fed has not allowed any undue expansion of the money supply. Whatever growth in the amount of money there has been has only been slightly in excess of the world's increased demand for money and money equivalents, and that is why inflation has been relatively low.


As the chart above shows, the world's demand for M2 money has been extraordinarily strong in recent years. Since early 2007, M2 has grown 26% more than nominal GDP, with the result that the ratio of M2 to nominal GDP has reached its highest level since the late 1950s. Monetary policy has been enormously accommodative, but at the same time money demand has been exceptionally strong. It follows that if the Fed hadn't been so accommodative, we could have suffered deflation and/or a weak economy, since the economy would have been starved for liquidity.


Since November 2008, the fastest-growing component of the U.S. money supply has been savings deposits, which have increased 68%, from $4 trillion to $6.7 trillion. The enormous growth in savings deposits has almost certainly not been driven by their attractive yields (which have been close to zero), so it must be due to an overwhelming desire for liquidity and safety. Consumers have been deleveraging and increasing their money balances to an exceptional degree because they have become more risk-averse. Most of the growth in the money supply has been due to an increased demand for money and safety.

And just as consumers have worked hard to increase their money balances, banks have been very willing to hold on to the extra bank reserves the Fed has created, as they have struggled to boost their reserves and fortify their balance sheets.

In a sense, the Fed has spent most of the past 5-6 years responding to an unprecedented increase in risk aversion, which has manifested itself in a tremendous increase in the demand for cash, cash equivalents, deposits, and bank reserves. This increased demand for safety and liquidity has been the flip side of an equally unprecedented decline in confidence and an increase in risk aversion.

All of this leads to the following conclusion: since the Fed's quantitative easing efforts to date have been only sufficient to satisfy a huge increase in the demand for cash, cash equivalents, and bank reserves, what will happen when the demand for safe and liquid assets declines? When confidence in the future returns? When risk aversion declines? Will the Fed be able to reverse its quantitative easing efforts in a timely fashion, before an excess of reserves and a declining demand for cash pushes inflation higher? As I mentioned in a post last December,

... the biggest risk we all face as a result of the Fed's unprecedented experiment in quantitative easing is the return of confidence and the decline of risk aversion. If there comes a time when banks no longer want to hold trillions of dollars worth of excess bank reserves for whatever reason (e.g., the interest rate the Fed is paying is no longer attractive, or the banks feel comfortable using their reserves to ramp up lending, or the public no longer wants to keep many of trillions of dollars in bank savings deposits), that is when things will get "interesting."

Stephen Williamson discusses this same issue in great detail here, but from a slightly different perspective. The common thread we share is that the thing to worry about going forward is a declining demand for cash, cash equivalents, and bank reserves, since that could result in higher inflation if the Fed fails to take offsetting measures (e.g., draining reserves and/or increasing the interest it pays on reserves) in a timely and potentially aggressive fashion. There is no a priori reason to think they can't, but there is certainly reason to be worried, since we are sailing in uncharted monetary waters.

Unfortunately, it's ironic and paradoxical that the Fed's efforts to supply additional reserves to the banking system—at a time when the banks have many times more reserves than they could possibly want—may be doing just the opposite of what the Fed intends. Instead of boosting confidence, the Fed may be contributing to worries about the future course of inflation and interest rates. More reserves are not going to increase bank lending, since banks already face zero constraint on that score. Will more reserves increase confidence, or will they just increase concerns about the future?

It's not clear at this point what will happen as the Fed increases its purchases of Treasuries and MBS and creates more bank reserves in the process. But as long as uncertainty exists—and the Cyprus bank deposit fiasco threatens to increase risk aversion in the Eurozone—the demand for reserves is likely to remain strong and inflation is likely to remain subdued. As for the economy, it looks like it is slowly healing and taking care of itself.

Thursday, April 12, 2018

Reading the yield curve's message

If you haven't already heard that an inverted Treasury yield curve is a good predictor of recessions, then either you haven't been reading this blog for long or you haven't been reading much in the financial press of late. (For background, see some earlier posts of mine on the subject here and here.) The subject has become the focus of attention in recent months because the yield curve has been flattening, which in turn has sparked concerns that the risk of recession is rising. These concerns are misplaced, as I explain below.

Chart #1


The top portion of Chart #1 is the standard way to display the status of the Treasury yield curve. It represents the difference between the two lines on the bottom portion: the difference or "spread" between 10-yr and 2-yr Treasury yields. The spread is effectively a measure of the slope of the yield curve, which indeed is relatively flat compared to where it was several years ago. But it's not flat nor is it inverted; it is still positively-sloped, and that means the market believes the Fed is justified in saying it plans to increase rates modestly over the next year or so. The relative flatness of the yield curve is not saying that the Fed is tightening too much or threatening growth, it's best characterized as the market's way of saying that economic growth expectations are neither exciting nor worrisome. I explain this a bit more below.

Chart #2

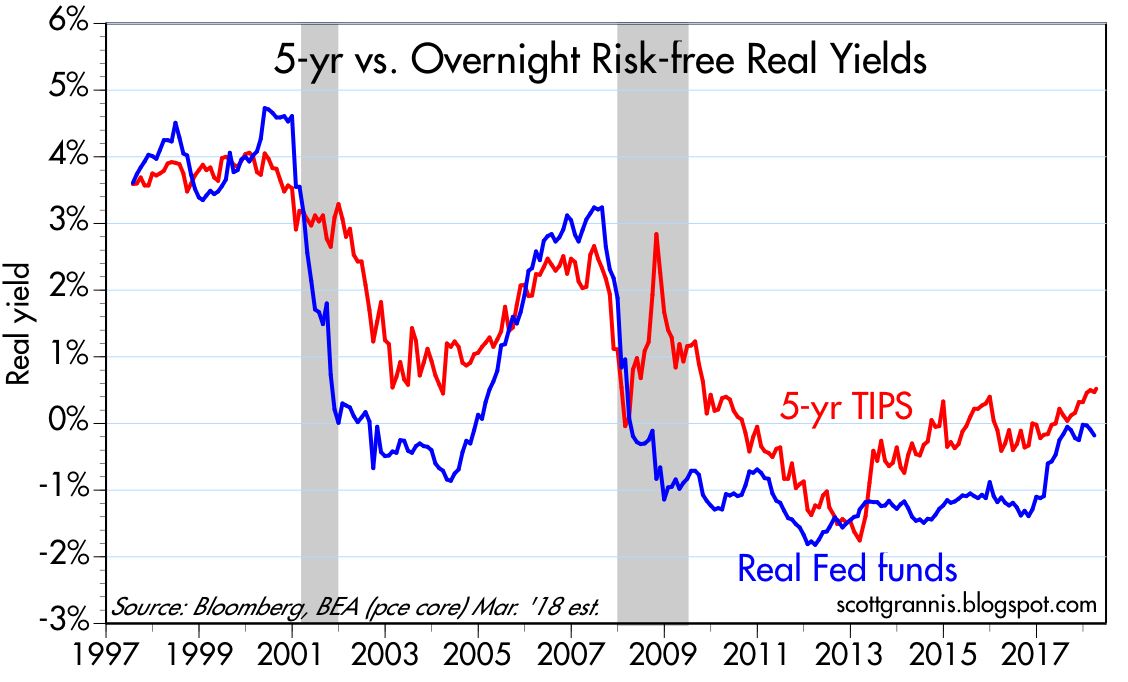
Chart #2 is another way of looking at the yield curve—a better way, since it gives us some important additional information. The red line in Chart #2 is similar to the blue line in Chart #1, but the blue line in Chart #2 is the important addition: it shows the real, inflation-adjusted Fed funds rate, which is the overnight rate that the Fed targets. The Fed these days has absolute control over the nominal funds rate, while the rest of the nominal yield curve is essentially a projection of what the market thinks the funds rate will average over time. Any yield curve analysis worth its salt should measure not only the slope of the Treasury curve, but also consider the level of the real Fed funds rate.

The Fed doesn't just target the funds rate. What it really targets—but rarely talks about—is the real funds rate. Borrowing money at 5% when inflation is 1% is one thing, but borrowing money at 5% when inflation is 10% is quite another (the former means borrowing is expensive, the latter means borrowing money is a good way to make money). Real borrowing costs are what truly affect behavior. When money is very expensive—when real borrowing costs are high—people are discouraged from borrowing and spending and are encouraged to save money; eventually, if real rates are forced too high, economic activity suffers. That's been the proximate cause of every one of the recessions in the past 60 years.

One thing that stands out in Chart #2 is that the real funds rate has been negative for the past decade. Doomsayers think this means the Fed has been flooding the world with money, and the sky will soon be falling. Monetarists reason that, since we have seen neither a collapse of the dollar nor soaring inflation over the past decade, this can only mean one thing: the demand for short-term financial assets has been incredibly strong for many years (another way of saying that the market has been very risk averse for most of the past decade), and, moreover, the Fed hasn't artificially depressed interest rates, nor has it flooded the market with money no one wanted. The Fed has kept rates low because the demand for money has been strong. See this post (The Fed is not "printing money") from five years ago for more background.

Chart #2 actually has two messages: 1) an inverted yield curve is a good leading indicator of a recession, and 2) very high real short-term interest rates are also a good leading indicator of a recession. When both those conditions hold, that's when you need to worry about a recession. Today we're not even close to having to worry. Despite the Fed having raised its target funds rate six times in the past 18 months (from 0.25% to today's 1.75%), the real funds rate is still in negative territory (-0.18% as of March 31 by my calculations), because inflation over the past year has been almost 2%. The Fed has raised its target for the real funds rate because the market has grown less risk-averse and economic growth expectations have improved somewhat. The Fed hasn't "tightened" in the sense that it is trying to slow things down. The Fed is just following the market.

Chart #3

Chart #3 is important because it gives us information about the slope of the real, inflation-adjusted yield curve. Real yields are just as important, if not more so, than nominal yields. The blue line, the real funds rate, is ground zero for the real yield curve, while the red line, the real yield on 5-yr TIPS, is the market's estimate for what the real Fed funds rate will average over the next 5 years. Today, the front end of the real yield curve is positively sloped (i.e., the spread between the two lines is positive), and it has actually been steepening since last summer. The message: the market agrees with the Fed that short-term interest rates, in real terms, will need to rise in coming years. Not by a whole lot, but by enough to rule out the notion that the market and/or the Fed are nervous about the health of the economy. The time to worry is when the real yield curve becomes negatively-sloped, as happened before each of the past two recessions (i.e., when the blue line exceeds the red line, because that means the Fed has tightened too much).

Another reason the Fed needs to raise real rates is to boost the attractiveness of the $2 trillion of excess bank reserves held by the banking system. Failing to do so would decrease banks' desire to hold excess reserves, and that in turn would lead to excessive lending, too much money, a weaker dollar, and rising inflation.

Chart #4

Chart #5

Chart #4 uses real and nominal 5-yr yields to give us information about the market's inflation expectations. Despite the Fed having kept real short rates negative for 10 years, inflation expectations today are no different from what they have been in the past. As Chart #5 shows, the CPI ex-energy has been on a 2% growth path for the past 15 years, and inflation expectations today, based on 5-yr TIPS and Treasury yields, are about 2.1%. That is effectively proof that the Fed has not been printing money or distorting markets. In monetarist parlance, the Fed has managed to keep the supply of money pretty much in line with the demand for money, though not completely, because inflation has averaged about 1.6% per year for the past 10 years.

Chart #6

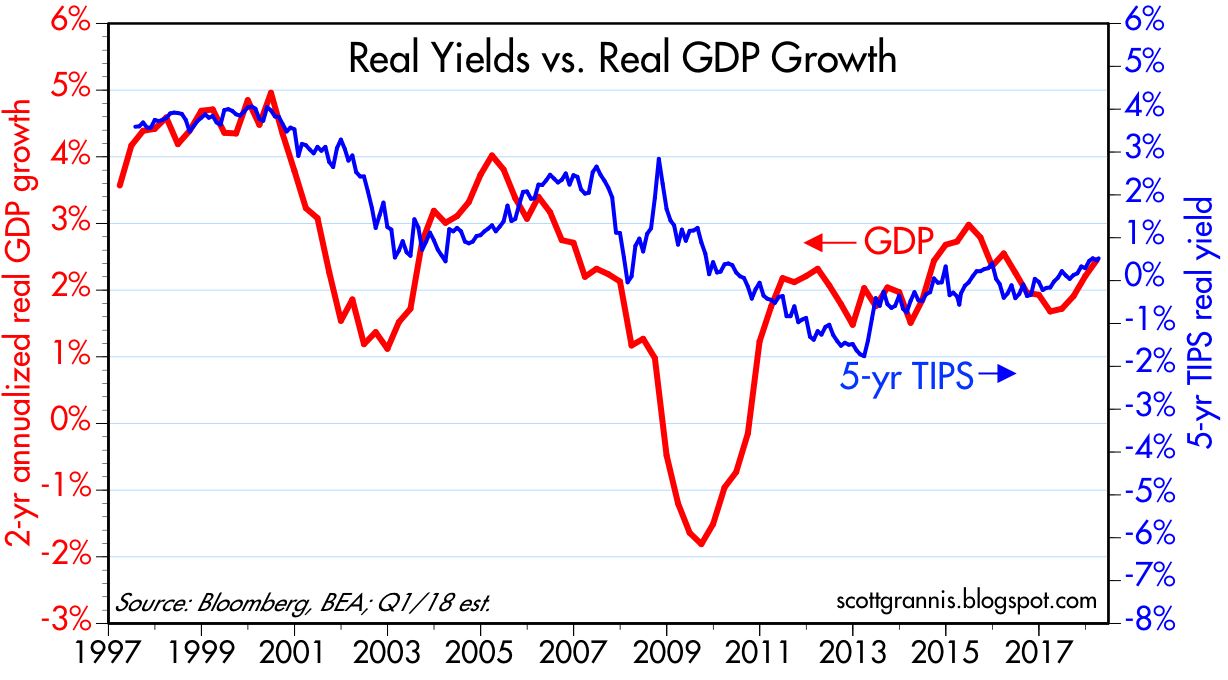
Chart #6 shows that real yields on TIPS also provide us with information about the market's GDP growth expectations. The level of real yields tends to track the level of real growth, and that is not surprising at all. A stronger economy implies higher real returns, and real yields should therefore rise in a faster-growing economy. Conversely, as economic growth weakens, as it did following 2000, real yields should fall. Currently, real yields of about 0.5% on 5-yr TIPS tell us that the market expects the economy is likely to grow about 2-2.5% per year, according to my reading of the bond market tea leaves.

If last year's tax reform results in a significant increase in economic growth, as I expect it will, then the Fed is going to have to guide real yields significantly higher as well. And that of course means significantly higher nominal yields, assuming inflation expectations remain "contained."

But for the time being, today's yield curve holds no threatening messages for the economy, and I think the market intuitively understands this.

What's worrisome today is not the yield curve, but the threat of a possible trade war with China and the ongoing tensions in the Middle East. The volatility that we are seeing is the result of the turbulence one would expect when headwinds (trade war risk, Middle East tensions) collide with tailwinds (last year's tax reform). For now, the market's judgment is that the two opposing forces effectively neutralize each other, with the result that growth is expected to be unimpressive, while inflation is expected to remain in the neighborhood of 2%.

Thursday, October 8, 2020

On the demand for money and other considerations


This blog has consistently employed a supply-side approach to fiscal policy (e.g., improving the incentives to work and take risk tends to lead to a stronger and more prosperous economy, as does reducing regulatory burdens) and a classic approach to monetary policy (e.g., inflation occurs when the supply of money exceeds the demand for it). In this post I focus on monetary policy, reiterating and amplifying observations that I have made over the past decade or so.

It's easy to measure the supply of money, and the Fed provides those statistics weekly. The M2 measure of money is broadly favored, and it is the one I have consistently used. More recently I have emphasized two components of M2—savings deposits and demand deposits—which together comprise about 75% of the $18.4 trillion M2. I have argued that these two measures are a good proxy for the demand for money, even as they are also measures of the supply of money. Both components represent money that has been set aside my consumers and businesses as a form of saving, security and/or comfort—essentially a hedge against risk. They are distinct from checking accounts and currency in circulation, since those are held primarily for convenience (e.g., to make monthly payments and to make miscellaneous purchases) rather as a risk-free store of money.

With the interest paid on savings deposits and demand deposits now hovering just above zero, it's easy to see why these deposits are a good proxy for money demand. Since they yield practically nothing, people hold them simply because they want a store of value that is easily accessible and relatively risk-free. For most of our history, these deposits paid an attractive rate of interest that was greater than the prevailing rate of inflation (i.e., real interest rates were positive). Those conditions (high interest rates) served to muddy the monetary waters, since it's tough to know whether people held these deposits as investments or merely as a store of value. Now, with interest rates at or near zero it's easy: they respond directly to people's demand for money and safety.

As I predicted back in 2009 and 2010, when the M2 measure of money was growing faster than ever before, the then-rapid growth of money would not be inflationary, because rapid M2 growth was being driven by strong growth of savings and demand deposits. The Fed was accommodating a huge increase in the demand for money; the Fed was NOT "printing money" with abandon as so many thought. (That includes yours truly, since I worried about rising inflation in late 2008 and early 2009. I later realized I was wrong.) The proof of the monetary pudding, as it were, was to be found in the fact that inflation has been low and relatively stable for a long time. Indeed, the world has worried more about deflation in the past decade than it has about rising inflation, despite rapid growth in the money supply.

How do you get low and even falling inflation when the supply of money is expanding rapidly, as it did in late 2008 and early 2009? It can only happen if the demand for money is growing as fast or faster than the supply of money. If a farmer is selling more apples every day it's because the demand for apples is also increasing every day; otherwise he would find himself with a glut of apples and would soon have to cut the price of his apples. A lower price would be required to bring demand back into line with supply.

What follows are some charts which focus on money supply and money demand. The story they are telling is similar to what it was a decade ago: incredibly rapid money growth is occurring because the demand for money is incredibly strong. The Fed is not printing money and so, for the time being at least, there is little risk of inflation.

Chart #1

Chart #1 shows the composition of the M2 measure of the money supply. Bank savings deposits make up by far the biggest portion, and they currently total almost $11.6 trillion. Currency is the next largest portion, currently totaling $1.9 trillion. One could argue that currency in circulation in a good measure of money demand, because nobody holds onto currency unless it serves them a purpose. It's complicated, however, because foreigners hold the vast majority of US currency. Do some math, and you will see that if $1.9 trillion of currency (mostly $100 bills) were held by only US residents, then each of us would be holding almost $6,000 in cash on average. Don't know about you, but my family rarely has more than $1000 in cash lying around or stashed under the mattress. Currency tells us a lot more about foreigners' demand for money than it does about the demand for money of US residents. Interestingly, currency has surged at a 23% annual rate since last February, which suggests the whole world is scared of Covid—which is not surprising since Covid is a problem everywhere. In any event, the Fed supplies currency only on demand, and in exchange for bank reserves, so the supply of currency and the demand for it are always in balance.

Chart #2

Chart #2 shows the level of the M2 money supply compared to the long-term trend rate of M2 growth (green), which has averaged about 6.5% per year for the past 20 years. M2 exploded starting last March, as the Fed pulled out all the stops and the federal government began mailing big checks to tens of millions of displaced workers and struggling businesses. M2 has now increased by about $3.2 trillion over the past seven months. Growth in savings and demand deposits account for about 80% of the increase in M2.

Here's the underlying and underreported story: federal debt has increased by almost the same amount ($3.4 trillion) as M2 has since last March. The Fed bought substantially all of the Covid-era federal debt (notes and bonds) issued by the federal government and paid for them with bank reserves. The banking system experienced an equivalent surge in deposits, which they used to buy the treasuries the Fed then bought from them. The banking system effectively "invested" their deposit surge in bank reserves. By buying over $3 trillion of treasuries, the Fed effectively converted (transmogrified, as I like to say) notes and bonds into short-term, risk free assets, since bank reserves are essentially T-bill substitutes which the banks find to be an attractive way to invest their deposit inflows. Bottom line, the increase in the money supply was driven by an equivalent increase in the demand for money and money equivalents. That's not inflationary. 

Chart #3

Chart #3 shows the 3-mo. annualized growth rate of savings and demand deposits, which was truly explosive from early March until just a few months ago. Note how this component of M2 also experienced rapid growth around the time of the Eurozone crisis in 2011, when money fled to the security offered by US banks. Note also how the growth of savings and demand deposits slowed in the wake of the Nov. '16 elections: money held in safe form flowed back into the economy as confidence increased and the economy prospered. If we're fortunate, the economy will sooner or later lose its fear of Covid and money will once again leave deposit accounts and go back into the economy, there to fuel rising consumption and an expanding economy.

It's important to note here that the growth rate of M2 has almost completely returned to what it was prior to the Covid crisis: in the past three months M2 has increased at about a 10% annualized rate, and in the three months prior to last March, M2 increased at about a 6% annualized rate. What that means is that demand for money is no longer rising by much. Thus the Fed has little reason and little need to continue to convert notes and bonds into T-bill equivalents. Simply put, there doesn't seem to be a need for much more "monetary stimulus" as it is incorrectly referred to (actually, it's just an accommodation of increased money demand).

Chart #4

Chart #4 compares the level of nominal GDP to the level of M2. Both have increased by about the same order of magnitude over the past 60 years. Until this year, that is. What's happening is that the economy has effectively and suddenly increased its desire to hold money rather than to spend it. This is a natural reaction to the great uncertainty and fear that the Covid crisis has caused. But as that tendency reverses—as the demand for money declines—there is plenty enough money out there to fuel a big increase in real and nominal GDP.

Chart #5

Chart #5 divides the level of M2 by the level of nominal GDP. I've labeled the result "money demand." I like to think of this as being a proxy for the amount of cash and cash equivalents the public wants to hold, expressed as a percentage of average annual income. Prior to the Covid crisis, as a country we were comfortable holding a cash and cash-equivalent reserve equal to about 70% of our annual income; now it's almost 90%. Money demand was relative stable for many decades, but it has increased dramatically in the wake of the Great Recession and now during the Covid panic. However, money demand is already beginning to decline. I've estimated the value of the ratio for the third quarter, assuming 10% annualized growth in M2 and a 30% annualized growth of nominal GDP. It will probably decline a lot more in the months and the years to come as confidence returns and the economy grows.

What happens when the demand for bank deposits declines? Let's say the public decides over the next year to withdraw $1 trillion of the $3 trillion they added to bank deposits this year. As the money is withdrawn, banks will no longer need $1 trillion of the bank reserves they "bought" this year. Banks can simply sell their reserves back to the Fed in exchange for notes and bonds. They can then sell the notes and bonds in exchange for cash which they can then distribute to those who are withdrawing their money. In the process, the demand for notes and bonds will decline, and that would likely translate into higher interest rates. Which is exactly what we would expect to happen as the economy recovers and returns to more normal conditions. If the Fed is on top of this development, they will happily sell notes and bonds and retire bank reserves, and the money supply will shrink in line with a reduction in money demand. But if the Fed insists on keeping plenty of reserves in the banking system, they would risk creating a surplus of money and that would be inflationary.

One soon reaches the conclusion that the Fed has been reacting to changes in the demand for money rather than stimulating anything. I and others have said this many times in the past. The Fed would have us believe they re setting the tone and the level of interest, when in reality they are simply accommodating the mood of the market. Whatever the case, it is clear that interest rates are extremely low not because the Fed has said so, but because the market's demand for short-term, cash-equivalent assets (e.g., T-bills and bank reserves) is enormous. The market is willing to pay such a high price for them that their yield has been pushed down to near zero. Thus, the prevalence of near-zero or even negative interest rates can mean only one thing: risk aversion remains very strong these days. The market is not exuberant or irrational. The Fed has not stimulated anything.
Chart #6

Chart #6 is my favorite way of seeing whether the Fed is behaving correctly. The blue line is the inflation-adjusted Fed funds rate (i.e., the Fed's target rate minus the year over year change in the Core Personal Consumption Deflator), and the red line is the real yield on 5-yr TIPS, which in turn is essentially the market's expectation of what the real funds rate will average over the next 5 years. When the blue line is below the red line, the Fed is behaving well and the economy is healthy, because the market is expecting the real funds rate to rise in the future. But when the blue line is above the red line this means the Fed is so "tight" that the economy is likely to weaken and the Fed will eventually need to lower the real funds rate in response. Today it looks like the Fed is just about right. 

The charts that follow are interesting in their own right, and help me to understand what's going on in the economy:

Chart #7

Chart #7 compares the price of gold to the price of 5-yr TIPS (using the inverse of their real yield as a proxy for their price). It's remarkable that the prices of these two completely different assets should be so closely correlated over so many years. I can only conclude that the market views both assets as "safe havens." Both provide insurance against nasty events: gold protects you from disasters of all sorts, and TIPS are guaranteed to protect you against a rise in inflation. Both prices appear to have peaked, which suggests that the demand for money and safety has peaked. That confirms the message of M2.

Chart #8

Initial claims for unemployment were disappointingly unchanged last week, but continuing claims continued their strong downtrend, as seen in Chart #8. From a peak of 25 million in early May, they are now down to 11 million. That means that at least 14 million people who lost their jobs have now gone back to work. In other words, 60% of the jobs lost have been recovered, which further suggests an ongoing decline in the rate of unemployment. That counts as a V-shaped recovery in may book. It's tragic, however, that there are still so many unemployed, and that their ranks are filled with the most vulnerable. The only solution for so much misery is to OPEN THE ECONOMY ASAP. Failing that, the government should somehow compensate the workers who have fallen on hard times directly as a result of terribly misguided public policy choices. 

Chart #9

Car sales, shown in Chart #9, have almost completely reversed their Covid plunge. Another V-shaped recovery.

Chart #10

CDS spreads, shown in Chart #10, are the most liquid measure of generic corporate credit risk. Happily, they are very low, as are swap spreads. This strongly suggests that liquidity conditions in the financial market are very healthy and the outlook for the economy is also very healthy. 

Chart #11

Chart #12

Charts #11 and #12 show that air travel is decidedly NOT enjoying a V-shaped recovery. For the past three months, gains in passenger traffic have been very small. Overall traffic today is still down some 66% versus year-ago levels. A sobering statistic. Fear of flying will be with us for a long time, it would appear.

Covid comments

Catching Covid is not a death sentence, as Trump has showed us: "Don't be afraid of Covid. Don't let it dominate your life." Very wise words from our Commander in Chief, who is unafraid to bow to the prevailing orthodoxy of fear. In that regard, Heather Mac Donald has a very good quote (HT Mark Perry):

"Reopening is still the right policy. Mandatory outdoor mask-wearing is merely a way for government to turn citizens into walking billboards of fear, sending the false message that danger is everywhere. Infection rarely leads to death. Most of the infected recover. Given his governmental duties, the surprise is that Trump—as president, another kind of front-line worker—has not gotten sick before now."

Don't miss the Great Barrington Declaration, an open letter signed by more than 7,000 mental & public health scientists and medical practitioners. In it they argue strongly for opening the economy, especially schools, while protecting the vulnerable (i.e., mostly the elderly and infirm). Here is a functioning link for the Great Barrington Declaration.

UPDATE: A MUST WATCH VIDEO by Dr Reiner Fullmich. An intelligent, well-argued brief for why there was never a Covid “pandemic.” It’s always been just a bad flu, as I and many others have been arguing since last April. Lockdowns have had no impact. Tests, as even the NY Times has admitted, cannot reliably detect Covid infections, and the vast majority of positive results are false positives. It’s a “case-demic” not a pandemic. Governments everywhere have systematically trampled the constitutional rights and liberties of their people without any justification. Watch it and weep for the miseries unnecessarily inflicted upon millions of innocent people and businesses.

Wednesday, March 19, 2014

FOMC moves in the right direction

In a few weeks, according to the report following today's FOMC meeting, the Fed will have "tapered" its purchases of bonds by about one-third (from $85 billion per month in December to $55 billion a month). And lo and behold, the sky has not fallen, nor is it about to. Nevertheless, the market continues to fret that tapering is a form of tightening, since, as the theory goes, the economy has managed to grow only thanks to Fed "stimulus," and that without it, economic activity will grind to a halt.

Never in my many years of Fed watching has there been so much confusion about how Fed policy operates.


The myth persists that QE bond purchases are "stimulative" because it involves the printing of massive amounts of money and the artificial depressing of yields. But this is simply not the case. As the chart above shows, 10-yr yields today are actually higher than they were when the Fed launched its first QE bond purchases. Bond prices have actually fallen despite $3 trillion of bond purchases by the Fed. The chart also makes it clear that yields have actually risen during each episode of QE bond-buying. Operation Twist (OT) was ineffective as well, since 10-yr yields were essentially unchanged during the period in which the Fed was buying 10-yr bonds and selling short-term bonds. The main determinant of yields is not the marginal purchases by the Fed, but the market's willingness to hold the entire stock of bonds (Treasuries, MBS, corporate bonds, etc., totaling many tens of trillions of dollars), since all bonds are priced off of Treasuries. That willingness, in turn, is a function of the market's expectations for inflation and economic growth.


As I've explained before, the Fed is not "printing money" when it buys bonds. When the Fed buys bonds it must buy them from banks. The Fed pays for the bonds by crediting banks' reserve account at the Fed. Bank reserves are not money that can be spent anywhere. They only exist on the Fed's balance sheet. Banks use their reserves to collateralize their deposits and to increase their lending, but to date the growth of the money supply has not been unusually rapid, as the chart above shows—only slightly more than 6% per year for the past 20 years. This is not to say that all will be A-OK forever, since the $2 trillion of excess reserves currently in the system would allow banks to expand their lending—and the money supply—by several orders of magnitude if they so desired.

When the Fed buys bonds, they become part of the Fed's assets. The Fed incurs a corresponding liability in the form of bank reserves. In effect, the Fed buys bonds from banks by borrowing the money from the banks to buy the bonds. The Fed pays the banks interest on their reserves of 0.25%, so from the banks' perspective, they are lending money to the Fed for a modest rate of interest which is actually better than they could get by buying T-bills, which currently yield only 0.05%.


As the chart above shows, the Fed's purchases of $3 trillion of notes and bonds (assets) have been offset by an approximately equal increase in currency (about $0.4 trillion) and bank reserves (about $2.6 trillion).

In addition to saying they will continue to taper their bond purchases, the FOMC decided to drop its 6.5% unemployment rate threshold. They will now consider a range of economic variables when deciding to taper and when and by how much to raise short-term interest rates. It's unfortunate that they have backed off of a rules-based policy and now have more discretion—which creates uncertainty—but at the same time this could give them more flexibility to act more or less aggressively if conditions warrant. Meanwhile, continuing to taper is definitely a step in the right direction since, as I've noted in recent posts, there are signs that the demand for bank reserves is declining and banks' willingness to lend is increasing.

Monday, May 13, 2013

Is a QE exit really scary?

With the publication over the weekend of a story by John Hilsenrath discussing the Fed's plans for exiting Quantitative Easing, it is clear that the time is rapidly approaching when the Fed will begin scaling back its monthly purchases of Treasuries and MBS. Once new purchases cease, the next step will be for the Fed to reduce its holdings of Treasuries and MBS, and at some point in this process, short-term interest rates will almost certainly begin to rise. The only thing newsworthy about this is that the unwinding of QE might start a bit earlier than the market has been expecting. In fact, the Fed could well start scaling back its purchases within a few months. So how scary is this?

It's very scary if you believe that the Fed's aggressive expansion of its balance sheet has been the main force sustaining and powering the recovery. Without continuing injections of tens of billions of bank reserves each month, how can the recovery continue, and won't higher interest rates threaten the recovery?

It's not scary at all if you believe, like I do, that the primary goal of QE was not to "print money" or stimulate the economy, but rather to satisfy the world's apparently insatiable appetite for safe-haven, risk-free assets. It's not unreasonable to think that now, after four years of recovery, with over 6 million jobs created, with industrial production having staged an almost-complete recovery, with housing starts and auto sales growing at double-digit rates, and with global equity market capitalization only 8% shy of its 2007 all-time high, the demand for risk-free assets is beginning to taper off. If the world is now beginning to feel more comfortable with the fact that economic and financial conditions have improved, and thus the risk of another collapse has receded, then it would be entirely appropriate for the Fed to begin tapering its balance sheet expansion, simply because there is no longer a need for it.

It's not scary if you realize that higher interest rates typically accompany a recovering economy. Higher interest rates only become a threat to growth after at least a few years of aggressive Fed tightening—when real interest rates approach 3-4% and the yield curve becomes inverted. We are still many years away from conditions such as these. The Fed is likely to get really tight only if the economy and/or inflation start to really boom.

It's also not scary if you realize that the end of Quantitative Easing means the end of an unprecedented experiment in monetary policy that held the potential for dramatically increasing inflation and undermining the value of the dollar—and that was thus a major source of uncertainty. The unwinding of QE means the beginning of the end of a major source of risk-stifling uncertainty, not a new source of uncertainty. It's just plain old good news. Maybe that's why the market today reacted to the news with equanimity.

I've explained in detail here how the Fed's purchases of Treasuries and MBS were not the equivalent of printing money; how they were instead the equivalent of swapping newly-created, risk-free T-bills for more risky notes and bonds; and how banks have been quite content to hold on to virtually all the extra reserves the Fed has created in the process. As I show in the charts that follow, there is no evidence in the money supply numbers of any unusual growth, and there is no evidence of unusual dollar weakness. Gold's recent decline and the relatively flat performance of commodities are more evidence that QE has not been an exercise in massive money-printing. Moreover, short- and long-term inflation expectations remain quite normal.


The chart above shows that Fed tightening has been the source of all the recessions since the late 1950s. Tightening shows up as a rise in the real Fed funds rate, and in an inversion of the Treasury yield curve. Currently, the real Fed funds rate is still negative, and the yield curve is still quite positively sloped. Monetary conditions are easy, and extremely unlikely to lead to a recession.


Financial conditions are about as good as they get. No sign in the above chart of any financial stresses or deterioration.


Swap spreads have traditionally been excellent coincident and leading indicators of financial market and economic health. Absolutely no sign here of any unusual systemic risk. Liquidity conditions are excellent. It would highly unusual for there to be any near-term economic deterioration given the current health of financial markets.


M2, arguably the best measure of the money supply, is growing only slightly faster than it has grown for the past 18 years. Faster M2 growth is most likely a sign of increased money demand, since the lion's share of M2 growth has been in bank savings deposits, a classic refuge of safety in times of uncertainty. Faster money growth that is driven by rising money demand is not the kind of money growth that creates inflation. We would have to see a significant decline in money demand for inflation to rise, and so far there is no sign of that.


To date, the Fed has injected over $1.8 trillion of bank reserves into the banking system as a result of its purchases of Treasuries and MBS. Of this amount, only $115.8 billion are "required" to back up the deposits of the banking system. That means that banks have been willing to accumulate over $1.7 trillion of reserves on their balance sheets, earning only 0.25%. Why? Because banks are unwilling to lend more and many people and many businesses are still reluctant to borrow and many are still trying to deleverage. There clearly has been no excessive lending taking place, and thus no unusual growth in the money supply. Banks see reserves as substitutes for T-bills: as safe assets with which to bolster their balance sheets in times of uncertainty. This may well change in the future, of course, and the Fed will need to withdraw reserves in a timely fashion lest they be used by banks to engage in a wild, free-for-all lending spree.


Gold and commodity prices can be very sensitive to monetary excesses and shortages. Both declined in the years leading up to 2002, a time when the Fed was demonstrably tight. Both rose in the wake of the Fed's dramatic attempts to ease policy from 2003 through 2007. Both fell as the financial crisis of 2008 unfolded, as the world's demand for safe money rose precipitously but the Fed was slow to react. Both rose from 2009 on, as the world began to fear that Quantitative Easing would unleash tremendous inflation pressures. Both have been flat to down in the past year or so, as it has become increasingly evident that monetary policy has not produced the much-feared results.


It's not surprising that the dollar is quite weak from an historical perspective, given the Fed's overtly accommodative policy and the disappointingly slow U.S. recovery. But the dollar is not collapsing, and it has actually strengthened a bit over the past year or so. No sign here of any unusual excess of dollars in the world.


The first of the above two charts shows 5-yr nominal and real yields and their difference, which is the market's expectation for the consumer price index over the next 5 years. The second chart shows the same relationship for 10-yr yields. Both show that inflation expectations remain "firmly anchored" as the Fed is wont to say.

All things considered, there is nothing very scary going on. The only thing to be worried about is that the Fed fails to reverse QE in a timely fashion, since that could unleash a tidal wave of inflation. In the meantime, it's a good thing that the Fed seems to want to accelerate the reversal of QE.

Monday, September 23, 2013

Fed tightening is the real issue, not tapering

The timing of when the Fed begins to "taper" its purchases of Treasuries and MBS—currently running at $85 billion a month—has been the source of much market angst in recent weeks. Many expected the tapering to begin this month, but now the guessing is that it may start next month or in December. In any event, it's really much ado about nothing, and let me explain why. Briefly, QE hasn't done much to change the money supply; it hasn't done much to stimulate the economy; it hasn't been inflationary; and banks already have an almost unlimited ability to expand lending. Since massive amounts of QE haven't done much (if anything) to help the economy or to create unwanted inflation, then tapering QE by a small amount isn't likely to hurt the economy or create deflation. And since banks already have enough reserves to support virtually unlimited lending, reducing the growth of bank reserves by a small amount is not going to materially slow or discourage bank lending going forward. It's almost a non-event.


As the charts above show, the Fed's Quantitative Easing purchases of bonds have not resulted in any undue expansion of the money supply. Put another way, the Fed has NOT been "printing money" as so many seem to think. The M2 measure of the money supply, arguably the best measure we have, has been growing only slightly faster than its long-term average rate of about 6% per year for the past five years during which we've had plenty of QE. The second of the above charts shows this same process on a shorter time frame. On the surface, there is nothing unusual going on with the money supply, despite the Fed's purchases of $2.7 trillion of Treasuries and MBS since September 2008.


If there is anything unusual going on with the money supply, it is bank savings deposits (above chart). Coming out of the last recession, bank savings deposits started growing at a very fast 10-15% per year clip. In the past year, growth has slowed a bit to a 9-10% annual pace. Bank savings deposits are now up over $3 trillion dollars in the past four years. This rapid growth of savings deposits owes much to the public's demand for safe-haven assets. This is simply more evidence that the world's demand for "money" has been very strong, and the Fed has simply accommodated this demand. That is entirely appropriate and not inflationary.


When it finally happens, the first phase of the tapering of bond purchases will mean that instead of buying $85 billion of Treasuries and MBS per month, the Fed will be buying $65 billion per month. As the chart above shows, that is a fairly small change on the margin. Bank reserves now total some $2.3 trillion, so the Fed's monthly additions of $85 billion represent an expansion of the existing stock of reserves of less than 4%.


Despite the trillions of QE, despite four years during which money market rates have been close to zero, and despite the fact that the federal government has borrowed and spent an additional $4.7 trillion since mid-2009, the economy has experienced its weakest recovery ever. What's going on?

If the most massive package of monetary and fiscal stimulus in the history of our country has produced the weakest recovery on record, a layman could be forgiven for thinking that without all this buying, borrowing and spending by our government, we would be in a depression.

But there's another and better way to see this: When the government borrows, it takes money from someone. When it spends, it gives that money to someone else. It takes from Peter and gives to Paul. That is only "stimulative" if Paul ends up doing something more productive with the money than Peter would have if he had kept it. It's much more likely that all the borrowing and spending has worked to depress the economy, not stimulate it. That's because the bulk of the deficit-financed spending has gone to fund transfer payments. We've borrowed money from the productive members of society and given it to the non-productive sectors. The money has been spent unwisely, inefficiently, and even wasted. That's a perfect prescription for slow growth. (And of course there's all the money that has been handed out in the failed pursuit of "green" technologies, the huge subsidies to agriculture, and the multitude of deductions in our tax code which basically amount to corporate welfare.) In short, the "spending multiplier, as we now know, is definitely less than 1.

Here's the real bottom line that I wish taxpayers would understand: if the government hadn't borrowed and spent so much money, we would probably be enjoying a stronger, more normal recovery.


Not only has real GDP growth been miserably slow, so has nominal GDP growth. It's a weakening trend that has been in place for many years.


And as the chart above shows, inflation has been very low for many years. In short, there is no evidence here to support the notion that the Fed's "stimulus" has stimulated anything.

Bank reserves are important because in our fractional reserve system banks need to have reserves to collateralize their deposit base (about $1 of reserves for every $10 of deposits). Prior to 2008, reserves paid no interest, so holding reserves (which banks have to buy with real money) represented a deadweight loss. By limiting the amount of reserves available to the banking system (one of the main functions of the FOMC), the Fed could effectively control the degree to which banks could expand their lending. Since late 2008, however, that changed completely. The Fed now pays Interest on Reserves, currently 0.25%. That means that reserves are no longer a deadweight loss, they are much more like T-bills. They are a short-term, liquid, default-free, interest-paying asset. Banks now have an incentive to hold reserves, whereas before they had a disincentive to hold reserves.

Bank reserves are now an asset, just like loans are. Banks now weigh the relative advantages of holding reserves versus making loans. Given the risks of lending money in a weak economic environment, does the prevailing level of interest rates offer a significantly higher risk-adjusted return than holding reserves? If so, banks have the ability today to lend with virtually no limit, by using their existing reserves to collateralize new loans. That they haven't done so means that they find holding reserves (which is equivalent to lending money to the Fed) more attractive than making loans to the public.


As the first chart above shows, banks have been increasing their lending, but at a relatively slow pace in recent years. As the second chart shows, C&I Loans (bank lending to small and medium-sized businesses) have been growing much faster, but still they have not exceeded pre-recession levels. The facts say that banks have simply preferred to accumulate lots of reserves rather than make lots of new loans.


The above chart shows exactly how much banks have stockpiled in the form of reserves that are in excess of what they need to collateralize their deposits. It also makes it clear that QE2 and QE3 made relatively modest incremental changes to excess reserve balances. Tapering, when it begins, will hardly be noticeable on this chart. 


Of the $2.7 trillion of bank reserves that the Fed has created in the past five years, only about $75 billion have gone into the category of "required reserves," or reserves necessary to collateralize increased deposits. Around $365 billion have been converted into currency. (Note: increased bank lending does not mean that total reserves decline; it only means that some reserves formerly considered "excess" become "required.")

Tapering QE is only threatening to the extent it starves the banking system for high quality, short-term assets. As I've argued since October 2008, and more recently here, the main objective of QE was not to stimulate the economy, but to satisfy the world's huge demand for safe money in the wake of the disasters that unfolded in 2008. And that, in the end, is the big question: is the demand for more safe assets still strong? If it is, then tapering runs the risk of starving the banking system for liquidity. If not, if demand for reserves is beginning to decline because banks are becoming more confident in the health of the economy, then tapering is the right thing to do and it shouldn't be a problem at all, as I explain above. In my post last week, I argued that the demand for safe assets is beginning to decline, but it is still in its early stages.

Tapering is the first step on the road to an eventual tightening of monetary policy, which I define as a Fed-induced increase in real short-term interest rates. Once the Fed tapers its bond purchases (and no longer purchases any Treasuries or MBS), then the next step will be to begin to raise the amount of interest it pays on reserves (currently 0.25%). But it's a very long road we're looking at. The Fed won't be tightening monetary policy for a long time, not until the economy becomes noticeably stronger. It may take 6 months or so to end QE3, and then it might be another 6 months or so before short-term interest rates start to go up. It might take years before real interest rates become high enough to present a problem to the economy.

Be sure to read Calculated Risk's excerpts of Vice Chair Dudley's recent remarks. If it were up to him, there would need to be substantial improvement in the labor market before he would even consider tapering, and that could take 6-9 months if not more.


The chart above compares the real Fed funds rate (the difference between the Fed funds target rate and the year over year change in the PCE deflator) with recessions. Note that every recession since 1960 has been preceded by a marked tightening of monetary policy, in which the real Fed funds rate reaches or exceeds 3%. Currently, the real funds rate is -1%. Again, it will be a long time before monetary policy becomes tight enough to worry about.

Rather than fret about tapering, it makes more sense to worry about who the next Fed Chairman is going to be. Tapering is like easing up on the gas pedal, so that the car accelerates at a slower pace. The more important phase of monetary policy will be tightening, which is akin to stepping on the brakes. Janet Yellen—the current favorite to succeed Bernanke—has the reputation of being a "dove," which means that she would likely be less aggressive when it comes to tightening than others, since she firmly believes that monetary policy has the ability to "stimulate" the economy. This is a theory that is not shared by most monetarists and supply-siders, who believe that money growth that exceeds the demand for money only causes more inflation, not more real growth.

John Hilsenrath, writing in today's WSJ, says "Yellen Would Bring Tougher Tone to Fed," while also noting that she "has pushed the Fed to use low-interest-rate policies to spur faster economic growth and bring down unemployment." Yellen may thus be the first Fed Chair to practice "tough dove love," a new style of monetary policy that will undoubtedly raise the market's level of uncertainty.

In order to reverse QE, the Fed will need to a) shrink the supply of bank reserves by selling bonds and/or not reinvesting interest or principal payments, and b) raise the interest rate paid on reserves. These actions must offset banks' declining demand for reserves and make the interest rate they receive on reserves attractive, on a risk-adjusted basis, relative to what they think they can earn by increasing their lending activities. To do less would be equivalent to creating a surplus of money (via excessive bank lending) that would likely fuel higher inflation.

The next Fed Chair will almost surely oversee the Great Unwinding of Quantitative Easing. If not done correctly, we could find ourselves in a world of hurt. Yelled appears to lack the proper understanding of the limitations of monetary policy, and so the risk of a Yellen Fed is that monetary policy could become inflationary. But in any event, this is a risk that is still out there on the far horizon.


Would a Yellen appointment be a reason to buy gold? Not necessarily. I would argue that even with gold's recent decline from $1900 to $1300, it is still priced to a lot of inflation that has yet to happen. In real terms, golds is still trading significantly higher than its long-term average (see chart above).


Would a Yellen appointment be a reason to sell the dollar? Again, not necessarily. Although the dollar is up 7-10% from its all-time lows two years ago, it is still very weak from an historical perspective, which means that a lot of bad news is still priced in.

Would a Yellen appointment be a reason to sell Treasuries and MBS? Probably. As I pointed out last week, interest rates are still relatively low compared to current inflation.

How about stocks? I'll leave that for a subsequent post.